How to File Taxes as a Business: Forms by Entity Type
Contents:
- The Problem
- Why Solve It Correctly
- Step-by-Step Solution
- Step 1: Confirm Your Exact Entity Type
- Step 2: File the Correct Form for Your Entity
- Step 3: Gather Financial Records Early
- Step 4: Account for Quarterly Estimated Taxes
- Step 5: File by the Entity-Specific Deadline
- A Personal Example
- A Regional Difference
- A Seasonal Timeline
- Examples
- Troubleshooting
- FAQ
- Can I switch my entity type to reduce my tax burden?
- Do I need an accountant to file correctly?
Business taxation in America traces back to colonial-era license fees charged to merchants and tradesmen, a far simpler system than today’s entity-specific tax code, though the underlying principle, that operating a business carries a tax obligation distinct from personal income, has remained constant.
The Problem
New business owners often don’t realize that the correct tax form depends entirely on their legal entity type, leading to filing errors, missed deductions, or costly amended returns.
Why Solve It Correctly
Filing with the wrong form or missing entity-specific deadlines can trigger penalties, interest charges, and unwanted IRS attention that a little upfront clarity easily avoids.
Step-by-Step Solution
Step 1: Confirm Your Exact Entity Type
Sole proprietorships, single-member LLCs, multi-member LLCs, S-corporations, and C-corporations each file using different forms, so confirm your entity’s current legal status before proceeding.
Step 2: File the Correct Form for Your Entity
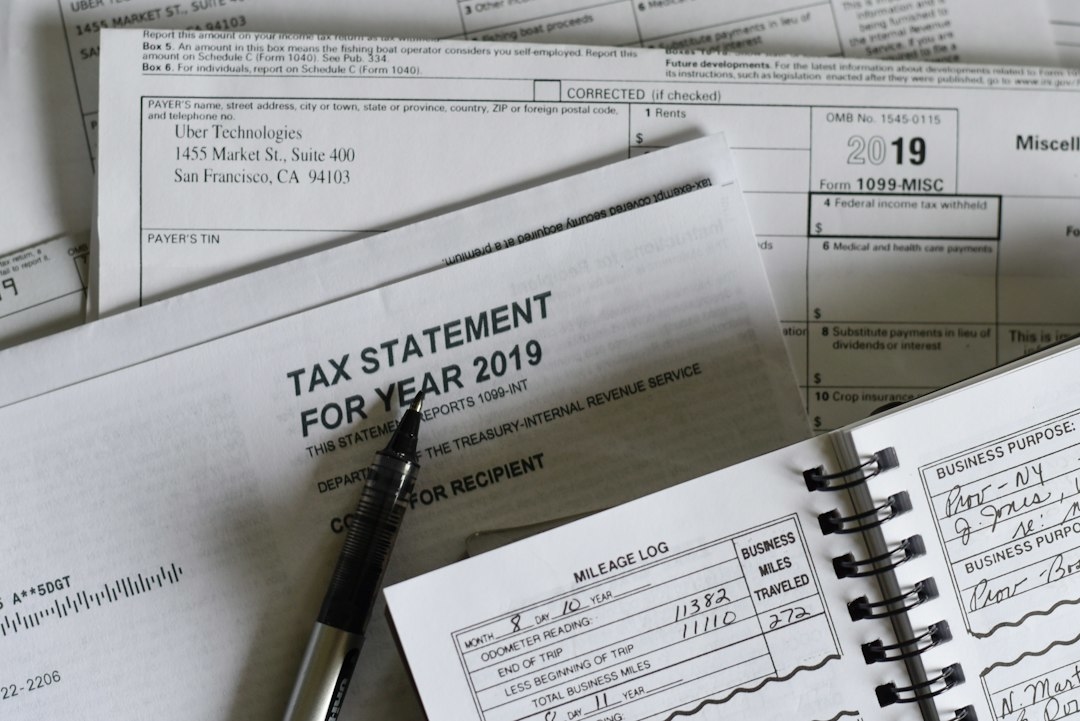
Sole proprietors and single-member LLCs use Schedule C attached to Form 1040. Partnerships and multi-member LLCs file Form 1065. S-corporations file Form 1120-S. C-corporations file Form 1120.
Step 3: Gather Financial Records Early
Profit and loss statements, expense receipts, and payroll records need to be organized well before the filing deadline to avoid a stressful last-minute scramble.
Step 4: Account for Quarterly Estimated Taxes
Most business owners, aside from those on a standard employer payroll, owe quarterly estimated tax payments throughout the year rather than a single annual payment.
Step 5: File by the Entity-Specific Deadline
S-corporations and partnerships face a March deadline, while sole proprietors and C-corporations typically face the standard April deadline, so calendar these correctly for your specific entity.
A Personal Example
A freelance web developer in Austin operating as a single-member LLC initially assumed she needed a separate business tax return, only to learn her LLC’s income simply flows through to her personal Schedule C, simplifying her filing considerably compared to what she expected.
A Regional Difference
Texas has no state income tax, simplifying filing considerably for Texas-based businesses compared to owners in states like California or New York, who must file corresponding state business returns alongside federal ones.
A Seasonal Timeline
Tax preparation realistically should begin each January as documents arrive, with a solid February target for having all records organized well ahead of March and April filing deadlines.
Examples
An S-corporation with three employees paid its owner a reasonable salary through payroll, then distributed remaining profit separately, a structure that reduced overall self-employment tax compared to an equivalent sole proprietorship.
Troubleshooting
If you’ve missed quarterly estimated payments, paying as soon as possible minimizes accumulating penalties, and a tax professional can help calculate the safe harbor amount that avoids further underpayment charges.
FAQ
Can I switch my entity type to reduce my tax burden?
Yes, many LLCs elect S-corporation tax treatment specifically to reduce self-employment tax once profit reaches a meaningful level, though this requires proper IRS election paperwork.
Do I need an accountant to file correctly?
Not always for a simple sole proprietorship, but multi-member entities and S-corporations benefit significantly from professional preparation given their added complexity.